The European chemicals industry faces a challenging landscape
through to 2029–2030, according to the latest industry
forecasts. Despite hopes for a cyclical rebound, sentiment is now
leaning toward a structural shift rather than merely part of the
typical cycle.
There are four key issues currently facing the European
chemicals market:
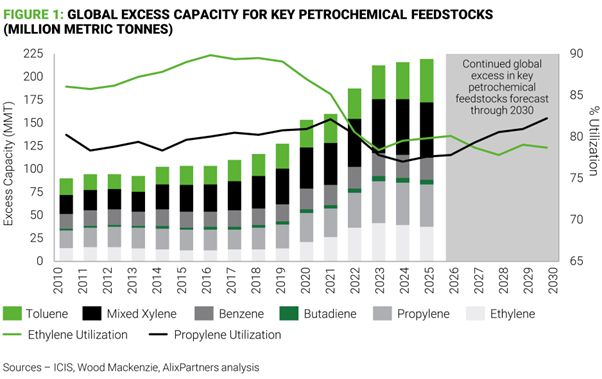
- No let-up in global overcapacity
Recent capacity additions, especially in Asia, have pushed
operating rates down towards 70%1in many European
countries, far below historical averages. The signs, however, are
that limited recovery is expected this decade.
Four new ethane-fed crackers (4.15 MMt/y combined) coming online
in Asia and Europe by 2027 will lower feedstock costs while further
expanding overall supply. Further global cracker capacity expansion
like this will drive the need for plant closures, especially assets
in high-cost regions such as Western Europe and Northeast Asia.
Japan will retire three naphtha





