Share on LinkedInShare on LinkedIn

ARTICLE · 03 JUNE 2024

Tax Requirements For Private Equity Funds In Germany: What You Need To Know

Private equity (PE) funds with at least two German tax resident investors are required to file an annual partnership tax return in Germany, even if they do not have taxable presence in the Germany.

GermanyTax

Background

Private equity (PE) funds with at least two German tax resident investors are required to file an annual partnership tax return in Germany, even if they do not have taxable presence in the Germany.

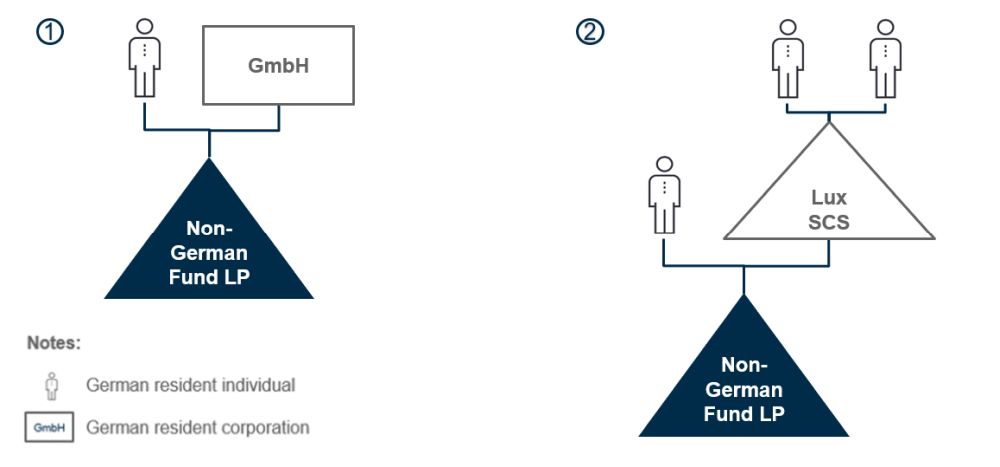
From basically 2023 onwards PE funds (not the German investors) are liable for filing a partnership tax return – comparable to a K-1 tax form in the U.S. – in the following scenarios:

  1. Two German residents (individual or corporate) directly invested in the fund.
  2. German tax residents invested in the fund via transparent non-German entities (e.g. Lux SCS).

1472536a.jpg

Failing to file the required annual partnership tax return in Germany may result e.g. in the fund's late filing penalties or in the tax authorities' tax estimate at the German investor level.

We operate a free-to-view policy, asking only that you register in order to read all of our content. Please login or register to view the rest of this article.

The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.

See more popular content from
