Share on LinkedInShare on LinkedIn

ARTICLE · 10 JULY 2013

Chambers As A Limited Company – Under The HMRC Microscope

HMRC is reviewing claims by members of such chambers with a view to recovering additional tax, and so it is important to have an agreement in place with HMRC.

United KingdomTax

Are you a member of chambers that operates as a limited company? If so, has chambers got HMRC approval for its members to receive full tax relief for their contributions to the chambers? HMRC are challenging barristers' tax deductions.

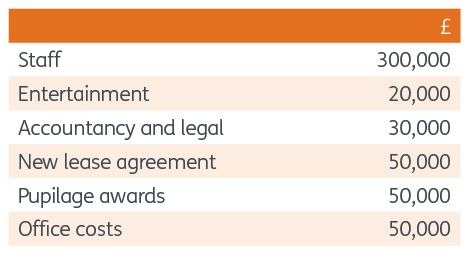
In this case, only £430,000 of the above costs is eligible for tax relief as the new lease agreement is capital and the entertainment costs are specifi cally not allowed for tax purposes. The member is therefore only able to claim tax relief for 430/500 x £25,000, which is £21,500, unless chambers has an agreement in place with HMRC for a different treatment.

HMRC is reviewing claims by members of such chambers with a view to recovering additional tax, and so it is important to have an agreement in place with HMRC. In the example above the total tax at stake for one year could be £32,900.

We operate a free-to-view policy, asking only that you register in order to read all of our content. Please login or register to view the rest of this article.

See more popular content from
