An example of evaluating the amount of risk and reward transferred and retained in a transfer in accordance with IAS 39 Financial Instruments Recognition and Measurement
Measuring the relative amount of risk retained by the transferor will be key to determining the accounting treatment for that transfer under IAS 39. The different treatments under IAS 39 are depicted below:
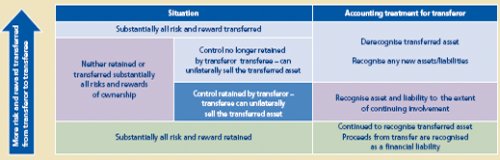
Often it will be obvious whether the transferor has transferred substantially all risks and rewards of ownership or retained substantially all risks and rewards and there will be no need to perform any computations. In other cases, it will be necessary to compute and compare the entity’s exposure to the variability in the present value of the future net cash flows before and after the transfer. The computation and comparison is made using as the discount rate an appropriate current market interest rate. All reasonably possible variability in net cash flows is considered, with greater weight being given to those





