Share on LinkedInShare on LinkedIn

ARTICLE · 20 SEPTEMBER 2016

IRS Issues Additional Guidance On REIT Parking Facility Income

Private Letter Ruling 201628020 provides a detailed analysis of when parking facility rent payments constitute rents from real property for REITs.

United StatesReal Estate and Construction

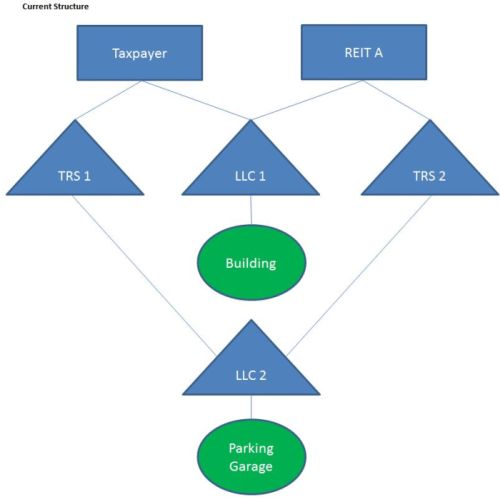
In the recently released Private Letter Ruling 201628020, the IRS considered a situation where affiliated entities owned various properties in an office park; the IRS determined that the entities' income from leasing space in a parking garage in the office park constituted rent from real property for purposes of the REIT qualification rules.

Taxpayer indirectly owned interests in a building and parking garage in an office park. The office park also included a second building owned by an unrelated entity ("Building 2 Owner"). The parties entered into a number of related agreements:

  • Parking Lease: Building 2 Owner entered into a long-term lease with LLC 2 pursuant to which LLC 2 was required to lease a number of parking spaces to Building 2 Owner.

We operate a free-to-view policy, asking only that you register in order to read all of our content. Please login or register to view the rest of this article.

See more popular content from
