Outstanding tax debts are, in principle, subject to forced
collection by the Luxembourg tax authorities. Recovery procedures
involve several phases and commencement is directly or indirectly
linked to the occurrence of the taxable event.
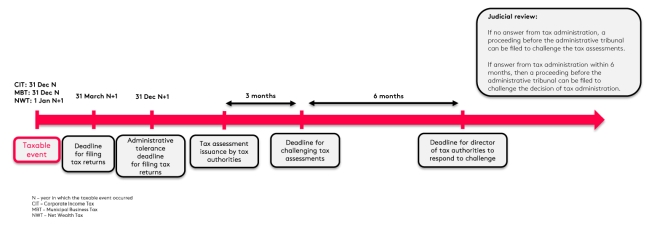
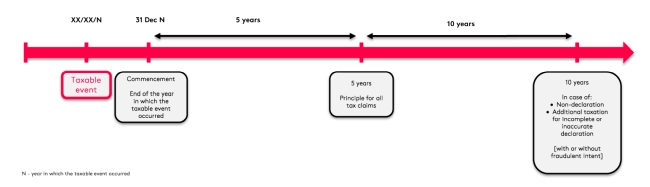
Below we summarise the main deadlines relevant in Luxembourg tax
filings and litigation proceedings, applicable statutes of
limitations, as well as the key steps of forced collection (based
on the taxpayer's country of residence).
Tax litigation main steps
Statutes of limitations
Forced collection of outstanding tax debts
Resident taxpayer
Administrative phase
- Warning sent by the competent revenue office for the
outstanding amount to be settled within 5 days








