The use of Spanish holding companies to invest in Latin America
("LATAM") offers a number of tax benefits for
investors.
These benefits come from the use of double taxation treaties
("DTT"), combined with a special tax regime in Spain for
holding companies (the "ETVE Regime"). Holding companies
taxed under the ETVE Regime are known as ETVEs.
As a result, channeling investments into LATAM countries through
a Spanish holding allows the optimization of the taxation on income
and profits distributed from a LATAM subsidiary.
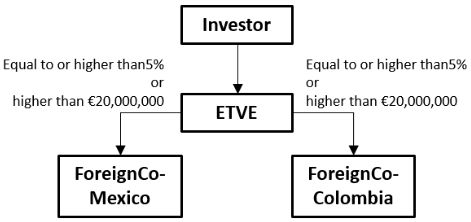
1. What is the ETVE Regime?
The Spanish Corporate Income Tax Law ("CIT
Law") foresees a special tax regime for holding
companies, the ETVE Regime, which provides for tax benefits at the
level of both the Spanish ETVE, and its shareholder. This special
regime is particularly favorable to non-Spanish tax resident
investors: