Share on LinkedInShare on LinkedIn

ARTICLE · 08 DECEMBER 2021

PART 4: Trust distributions are under ATO attack, are you ready?

Article considers the third primary defence to s100A.

AustraliaTax

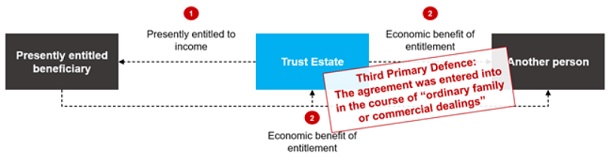
This week in our section 100A series, we consider the third primary defence to section 100A, which is to show that the agreement was not a "reimbursement agreement" because it was entered into in the course of "ordinary family or commercial dealing".  Such an agreement is expressly carved-out from the operation of section 100A.1

1139534a.jpg

What is that meaning of "ordinary family or commercial dealing"? 

The meaning of "ordinary family or commercial dealing" for the purposes of section 100A is presently unclear.  The legislation does not define what an "ordinary family or commercial dealing" is, nor does case law provide a clear meaning of the term in the context of section 100A.  The genesis of the term came from a Privy Council decision in Newton v Federal Commissioner of Taxation  (1958) 98 CLR 1.  That case, however, was about section 260 of the Income Tax Assessment Act 1936  (Cth) - the predecessor to Part IVA - and not about section 100A.

We operate a free-to-view policy, asking only that you register in order to read all of our content. Please login or register to view the rest of this article.

The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.

See more popular content from
