The UCITS IV Directive is set to level the playing field
in the European asset management industry. But how will the
Directive translate in the world of tax?
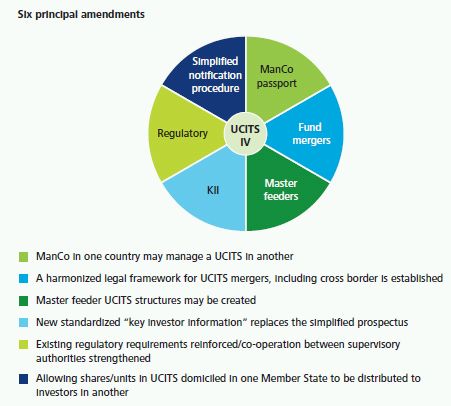
The European Parliament adopted Undertaking for Collective
Investment in Transferable Securities (UCITS) IV in January 2009
with the aims of further strengthening the harmonized regime for
investment funds, implementing measures to reduce time delays and
costs for bringing investment funds to market and more generally
making operations and distribution more cost efficient.
The six principal amendments, shown left, will be made to the
UCITS regime as part of the Efficiency Package.
However, the Directive does not include amendments in respect of
tax. It is recognised that, taken in isolation, the proposals
should result in a reduction of the number of management companies,
a new wave of fund mergers and master feeder structures as the key
avenue into new markets. However, any restructuring of funds






